
यह भी देखें
 12.11.2026 08:58 AM
Global equity markets are down today: Nasdaq 100 futures are off about 1.2%, and S&P 500 contracts are down 0.5%, giving back part of yesterday's gains. The MSCI Asia Pacific index slipped by 0.9% and looks set to break a three-day rally, while Taiwan's tech index plunged by 2.6%. The catalyst is a leadership crisis at Nvidia, whose shares lost another 10% yesterday.
According to reports, the company and an outside adviser are vetting potential successors to Jensen Huang after allegations of multiple extramarital relationships, one reportedly involving a woman suspected of spying for China. Recall that on November 9, the board already opened an independent investigation, with shares closing down 4.3% at the start of the week. Discussion has shifted from reputation to the question of whether the company can operate without its CEO.
The blow came just as the market was trying to recover. On Wednesday, US stocks rallied: CoreWeave jumped by 25% after a strong outlook, OpenAI reported quarterly revenue of $10 billion, and Anthropic's IPO demand was reportedly several times oversubscribed. The Nasdaq 100 added 2.3%, and the S&P 500 rose by 1.3%. Note that a week earlier, the tech sector crashed on fears of tougher AI oversight after Democrats' midterm wins, when the Nasdaq 100 dropped by 6.4% in a single day. Many analysts argue that Nvidia's role in funding the ecosystem makes a leadership change a systemic risk for the entire AI chain.
The market is also pressured by expectations of tighter Fed policy. The US dollar index remains elevated after Wednesday's 18-month high as traders fully price in a 25-bp hike in December and assign a small chance to a 50-bp move. For comparison, on November 9, the odds of a December hike were around 78.8%, rising to 96.3% after Waller's speech. Several commentators note that a 50-bp step or an acceleration to more frequent hikes has become a realistic possibility. After the US holiday break, long-dated Treasuries moved: the 30-year yield fell by 2 bps to 5.33%, while the 10-year sits near 4.99% versus 4.87% earlier in the week. The yen trades near 160 per dollar, and the Indonesian rupiah hit a record low, prompting intervention by the central bank.
Ahead lie several events that could set the tone. Friday brings US producer prices after October's CPI beat. Anthropic will price its IPO on November 18, with trading to start on November 19, and the Fed announces its interest rate decision on December 9.
In the Middle East, tensions between Iran and the US remain muted, and regional output is rising, so oil is moving toward a two-month low. Brent is trading below $92 after a 1.4% rise on Wednesday, versus roughly $116 on October 30. Gold has fallen again today, extending Wednesday's losses following hot US inflation and hawkish Fed comments. Currently, the metal is trading below $4,100, compared to $4,122 on Monday.
All this suggests that the market has entered a phase where strong AI headlines no longer offset governance risk. I expect pressure on the tech sector to persist at least until the Nvidia situation is resolved. Meanwhile, safe-haven demand for bonds will likely be temporary while the Fed prepares to tighten. Near-term tests are US PPI data and the Anthropic IPO. If neither supports sentiment, indices are likely to fall further, with the dollar remaining near recent highs.
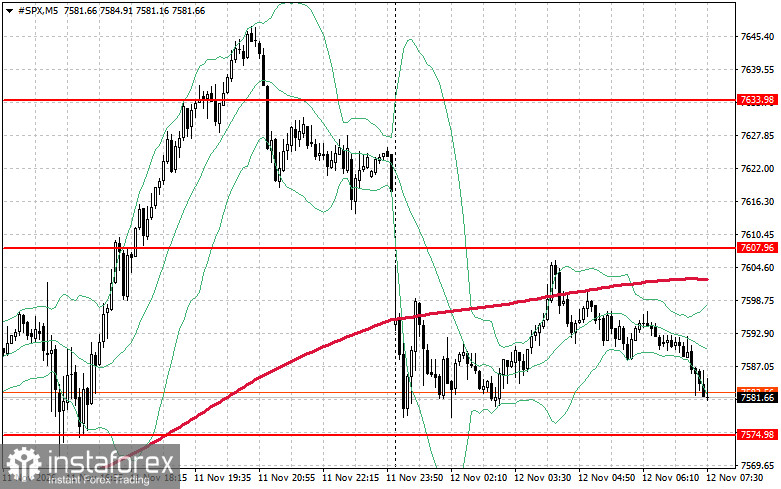
As for S&P 500 technicals, today's main task for buyers is to overcome the nearest resistance level of $7,607. That would confirm upside momentum and open the way toward $7,633. Equally important for bulls is control above $7,656, which would reinforce buying positions. On any downside move amid falling risk appetite, buyers must defend around $7,574. A break below that level would quickly push the instrument back to $7,544 and open the path to $7,518.

